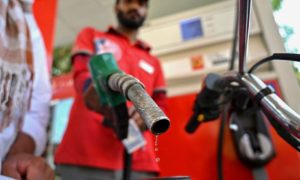






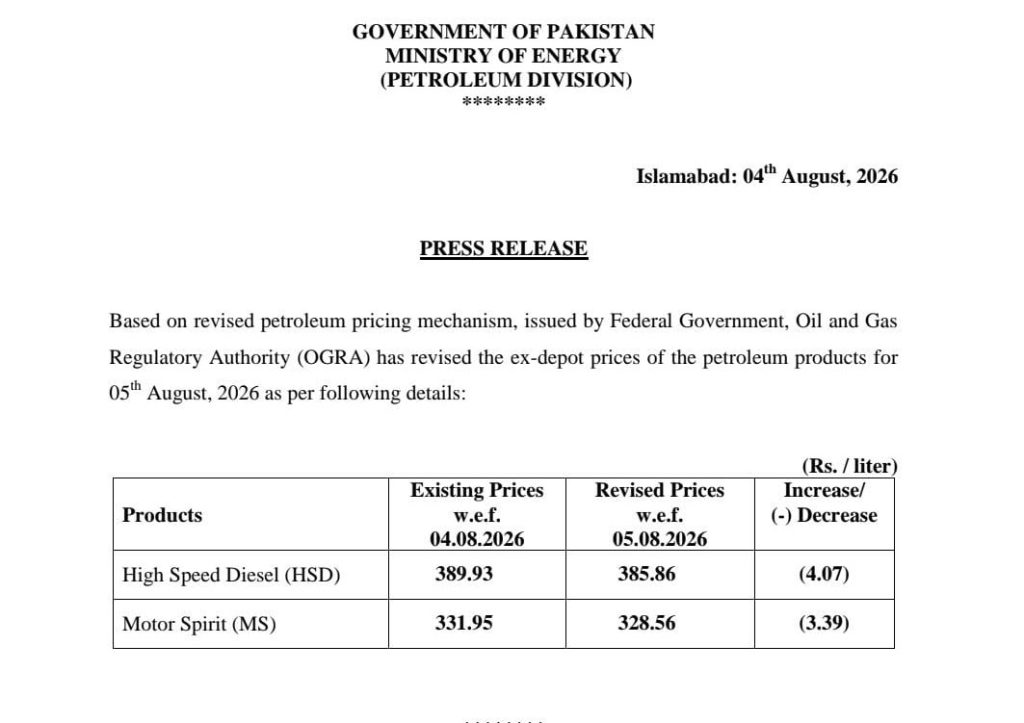
ISLAMABAD: Pakistan’s government has reduced petrol price by Rs3.39 per litre and high-speed diesel price by Rs4.07 per litre, effective from August 5, while simultaneously transitioning to a daily fuel price review mechanism to ensure transparency and align with international market fluctuations.
The new rates, announced through an official notification, set petrol at Rs328.56 per litre and high-speed diesel at Rs385.86 per litre, marking a modest but welcome reduction for millions of Pakistanis grappling with rising living costs.
The price cut comes amid renewed volatility in global oil markets triggered by escalating tensions in the Middle East.
Read Also: Pakistan Cuts Petrol Price by Rs4.08, High-Speed Diesel by Rs2.45 Per Litre
Daily pricing system replaces fortnightly reviews
Under the newly approved federal cabinet framework, the Oil and Gas Regulatory Authority (OGRA) will now issue ex-depot prices of petrol and high-speed diesel on a daily basis, moving away from the previous fortnightly review system. The daily pricing mechanism is designed to pass on the immediate impact of international price fluctuations to consumers while ensuring greater transparency.
According to Petroleum Minister Ali Pervaiz Malik, the daily pricing is based on a seven-day weekly average of international market prices, aligning Pakistan’s fuel pricing structure with international standards.
The regulator has been authorised to announce daily prices without requiring prior approval from the prime minister or the federal government, streamlining the decision-making process.
Under the new framework, prices notified on Fridays will remain unchanged on Saturdays and Sundays. The document further specified that OGRA will publish daily Platts reference prices from July 1, 2026, and the petroleum levy cannot exceed the limit approved by the federal cabinet. Any change in the levy rate will require approval from the Finance Division.
Global volatility drives policy shift
The government’s decision to adopt a daily price review mechanism was prompted by persistent volatility in global oil rates and the Middle East conflict.
The conflict began on February 28 when Israel and the United States attacked Iran, leading Tehran to shut the Strait of Hormuz, a critical chokepoint through which approximately one-fifth of global energy supplies passed before the war.